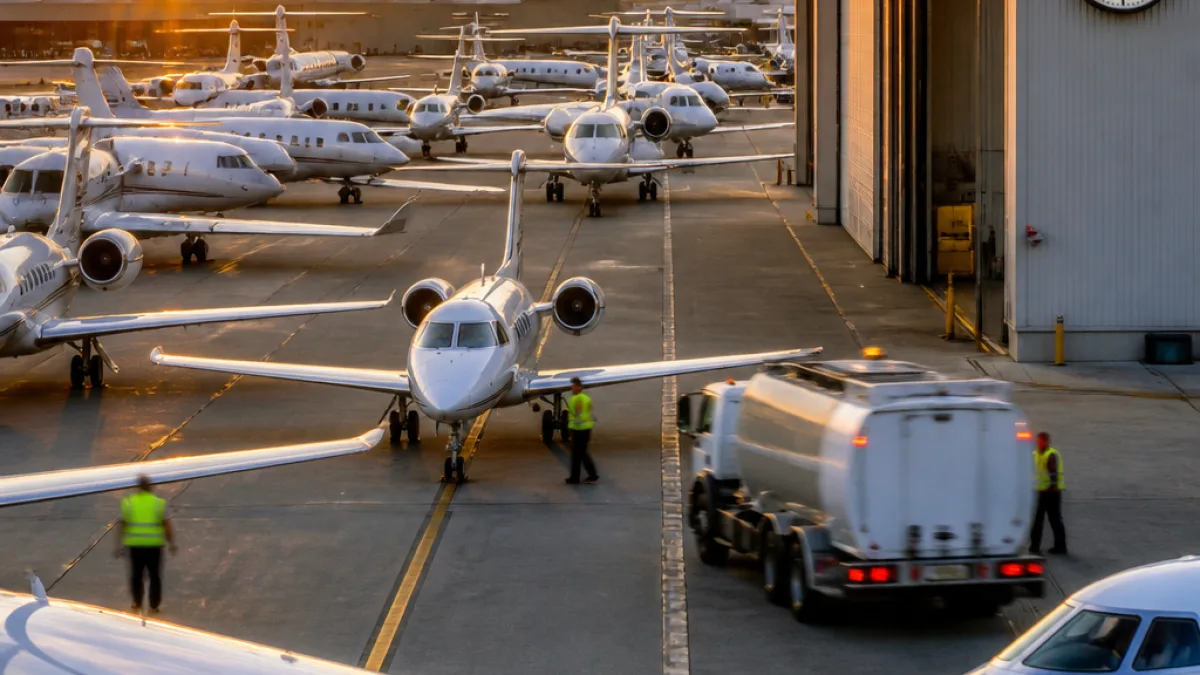
A McKinsey analysis of the private aviation market finds that the sector is no longer defined purely by aircraft supply, but increasingly by the ability to secure and coordinate the infrastructure and services that surround those aircraft.
“The defining question is no longer who can provide an aircraft, but who can secure and coordinate the capacity around it, from delivery slots, crews, hangars, and maintenance to a seamless passenger experience,”
McKinsey highlights that the Covid pandemic accelerated long-term change rather than producing a short-lived rebound. While commercial airline traffic took nearly four years to return to pre-pandemic levels, business aircraft flight hours recovered by the following year and have continued to expand.
Growth by the numbers
The report sets out several headline figures that underline the expansion of private flying:
- 4.9% annual increase in business aircraft departures since 2019
- 3.9 million business aircraft departures recorded last year
- 70% of global business flight hours in 2025 were accounted for by North America
McKinsey also notes structural shifts: the population of ultra-high-net-worth individuals (UHNWIs) grew at 5.6% annually from 2019 to 2025, nearly double global GDP growth, and has been a material demand driver.
Shifting demand and fleet trends
Demand patterns have moved away from traditional corporate hubs towards leisure and second-home destinations. McKinsey documents declines in short routes — a 4.4% reduction over six years — which private aviation is partly absorbing as commercial services contract. Specific airport impacts include falling private jet departures at Chicago Midway, Oakland San Francisco Bay and Van Nuys (Los Angeles), while Florida airports such as Fort Lauderdale-Hollywood, Miami International and Witham Field have seen increases. Mountain and resort airports including Rifle (Colorado), Jackson Hole (Wyoming) and Bozeman (Montana) have also recorded growth.
Fleet composition is polarising: very-light jets have expanded at 6.7% per year since 2019, while the long-range jet segment has grown at 5.1% annually. Over the longer term McKinsey notes the long-range fleet rose from 432 aircraft in 2000 to 4,448 in 2025.
Operational and infrastructure consequences
McKinsey warns that the industry’s immediate competitive question centres on access to supporting capacity: delivery slots at completion and delivery centres, trained flight crews, hangar and maintenance space, and ground-service capability to deliver a seamless passenger experience. These constraints affect not only operators and fractional programmes but also airports and MRO providers planning capacity and investment.
| metric | value (as reported) |
|---|---|
| Annual departure growth since 2019 | 4.9% |
| Business aircraft departures last year | 3.9 million |
| North America share of flight hours (2025) | 70% |
| UHNWIs annual growth (2019–2025) | 5.6% |
The report’s findings signal clear demand for investment across the business aviation ecosystem: airports that serve leisure and second-home markets may continue to see increased GA traffic; MROs and fixed-base operators will face pressure to expand capacity; and manufacturers and completion centres will need to coordinate delivery planning with operators to avoid bottlenecks. McKinsey’s framing shifts the industry debate from pure aircraft supply to the wider logistics and service network that determines whether growth can be absorbed efficiently and safely.