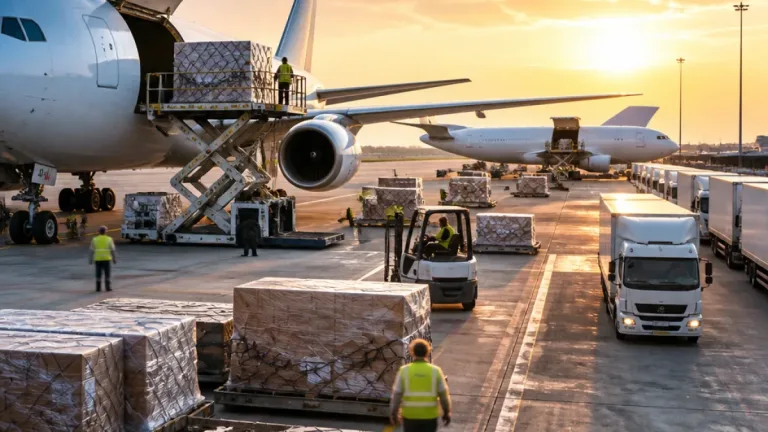
The airfreight sector is operating in a paradox: sustained demand growth driven by manufacturing and high-tech supply chains is colliding with sharply increased costs across the supply chain for aircraft, engines and maintenance. Market specialists and appraisal firms told attendees at the Cargo Facts Symposium in Nashville that these twin forces are reordering the economics of freighter fleet expansion and conversions.
Demand up, costs up even faster
Industry data show demand remains healthy: IATA reported airfreight traffic was up 4.4% year on year in August, supported by stronger manufacturing activity in North America and Asia Pacific, a panellist quoted the association as saying. Airbus’ 2026 Global Market Forecast projects airlines will need 2,670 additional freighters over the next 20 years to handle replacement and growth requirements, signalling long-term demand for large- and mid-size cargo jets.
Yet meeting that requirement is becoming more expensive. Lease rates and second-hand values for candidate conversion types have risen markedly, shrinking the margin on conversion projects and raising capital demands for airlines and lessors.
Used values and lease rates are climbing
Speakers at the symposium highlighted steep moves in valuations. According to Anna Kopinski, director of asset valuations at mBa Aviation, lease rates for older Boeing 777-300ERs — types regarded as prime candidates for freighter conversion — have risen by about $200,000 per month during the past two years. Kopinski added that the oldest 777s, which were worth roughly $30m at end-2024, are now effectively unobtainable below an estimated $40–45m.
“Now, you can’t get a half-time aircraft for anything under [$40-45m],” Anna Kopinski said.
Engine and component prices are also a major factor. George Dimitroff, head of valuations at Cirium Ascend, pointed to strengthened pricing for mid-life narrowbodies: midlife Boeing 737-800s are trading at around $20m, valuation levels that make subsequent freighter conversion financially feasible only when the conversion and engine costs stack up.
Capacity mismatch and conversion demand
Industry figures point to a structural mismatch: forwarders and integrators are seeking more lift, particularly for high-value, time-sensitive goods, even as the pool of suitable aircraft tightens. “Cargo demand is outpacing cargo capacity,” Pooja Gardemal, managing director at BK Associates, told the event, underscoring why airlines and lessors are under pressure to secure assets.
The combination of stronger demand and higher acquisition costs means airlines, lessors and conversion shops must weigh higher capital commitments against uncertain operating-cost trajectories such as jet fuel and engine maintenance. That calculus will shape which types are converted, who invests in new-build freighters and how quickly operators move to refresh ageing 747-400 and older fleets.
- Short-term pressure: rising lease rates and used-aircraft prices tighten conversion economics.
- Medium-term need: Airbus expects 2,670 freighters will be required over 20 years.
- Market winners: operators able to secure favourable financing and engines will be best placed to expand capacity.
| item | figure |
|---|---|
| IATA airfreight growth (August) | 4.4% y/y |
| Airbus freighter requirement (20 years) | 2,670 aircraft |
| Lease rate increase cited for 777-300ERs | $200,000/month |
| Oldest 777 estimated value (end-2024) | $30m |
| Current lower-bound estimate for those 777s | $40–45m |
| Midlife 737-800 trading level | $20m |
For operators planning fleet moves the message is clear: demand alone does not guarantee profitable expansion. The costs of aircraft, engines and maintenance must align with conversion and lease economics, and that alignment is currently under strain. Decisions taken now on whether to convert older types, place new-build freighter orders or secure long-term leases will determine capacity availability and pricing in the freight market over the coming years.